Financial and Practical Applications
1. Budgeting and Money
Learning outcomes
- I can create a simple budget using income and expenses.
- I can calculate savings and spending amounts.
- I can compare financial options using mathematical reasoning.
- I can interpret financial information presented in tables and charts.
- I can make informed decisions using numerical data.


What Is a Budget?
A budget is a plan for how money will be received, spent, and saved over a particular period of time.
A budget might cover:
- one week
- one month
- one year
- a particular event
- a project
- a trip
The basic idea is:
Income − Expenses = Money Remaining
The money remaining could be saved, invested, kept for future expenses, or used for additional spending.
Why Do People Use Budgets?
Money is limited, but people usually have many possible ways to use it.
A budget helps organize these choices.
For example, someone might need money for:
- housing
- food
- transportation
- utilities
- education
- entertainment
- savings
- unexpected expenses


A budget allows a person to compare available income with planned expenses before making financial decisions.
Income
Income is money received.
Examples can include:
- wages or salary
- allowance
- business income
- scholarships
- interest
- investment income
- gifts
- freelance work
Suppose someone earns:
$600 per month
from part-time work and receives:
$100 per month
from another source.
Total income:
$600 + $100 = $700
Expenses
An expense is money that is spent.
Suppose monthly expenses are:
| Expense | Amount |
|---|---|
| Transportation | $80 |
| Food | $180 |
| Phone | $40 |
| Entertainment | $70 |
| Clothing | $50 |
| Other | $30 |
Total expenses:
80 + 180 + 40 + 70 + 50 + 30
= $450
If income is $700:
$700 − $450 = $250
There is:
$250 remaining
Income, Expenses, and Balance
A useful budget equation is:
Balance = Income − Expenses
If:
Income > Expenses
there is a surplus.
If:
Income = Expenses
the budget is balanced, but there is no remaining amount.
If:
Expenses > Income
there is a deficit.


Example: Budget Surplus
Monthly income:
$1,200
Monthly expenses:
$950
Calculate:
$1,200 − $950 = $250
The budget has a:
$250 surplus
Example: Budget Deficit
Monthly income:
$900
Monthly expenses:
$1,050
Calculate:
$900 − $1,050 = −$150
The budget has a:
$150 deficit
This means planned spending is $150 greater than income.
Creating a Simple Budget
A useful budgeting process is:
Step 1: Determine total income.
Step 2: List expected expenses.
Step 3: Calculate total expenses.
Step 4: Subtract expenses from income.
Step 5: Decide how much money should be saved.
Step 6: Adjust spending if necessary.
Step 7: Compare actual spending with the original plan.
A budget is useful only if it is realistic and updated when circumstances change.
Fixed and Variable Expenses
Expenses can behave differently.
A fixed expense generally stays the same over a particular period.
Examples might include:
- rent
- subscriptions
- loan payments
- some insurance payments
A variable expense can change.
Examples include:
- groceries
- transportation
- entertainment
- electricity
- clothing


Knowing which expenses can change makes it easier to adjust a budget.
Needs and Wants
Another useful way to examine spending is to distinguish between needs and wants.
A need is something considered necessary for basic living or important responsibilities.
Examples may include:
- basic food
- housing
- necessary transportation
- essential clothing
- required school materials
A want is something desirable but not essential.
Examples might include:
- entertainment subscriptions
- restaurant meals
- upgraded electronics
- luxury clothing
- optional entertainment
The distinction is not always absolute. A particular expense may be a need for one person but a want for another depending on circumstances.
Calculating Savings
Suppose monthly income is:
$1,500
and expenses are:
$1,180
Money remaining:
$1,500 − $1,180 = $320
If all of the remaining money is saved:
Savings = $320
If only $200 is saved:
$320 − $200 = $120
remains available for other purposes.
Savings Rate
Savings can also be expressed as a percentage of income.
The basic calculation is:
Savings rate = Savings / Income × 100%
Suppose:
Income = $2,000
Savings = $300
Calculate:
300 / 2000 × 100% = 15%
Therefore:
Savings rate = 15%


Finding Savings from a Percentage
Suppose someone decides to save:
20% of $1,800
Convert:
20% = 0.20
Calculate:
0.20 × $1,800 = $360
Therefore:
Savings = $360
Money available after setting aside savings:
$1,800 − $360 = $1,440
Using Percentages to Build a Budget
Percentages can help divide income into categories.
Suppose monthly income is:
$2,000
A hypothetical budget allocates:
Housing = 35%
Food = 15%
Transportation = 10%
Savings = 20%
Other spending = 20%
The amounts would be:
Housing:
0.35 × 2000 = $700
Food:
0.15 × 2000 = $300
Transportation:
0.10 × 2000 = $200
Savings:
0.20 × 2000 = $400
Other:
0.20 × 2000 = $400
Total:
$2,000
These percentages are illustrative rather than a rule for how everyone should budget.
Visualizing a Budget
A pie chart is useful for showing how a total amount is divided among categories.
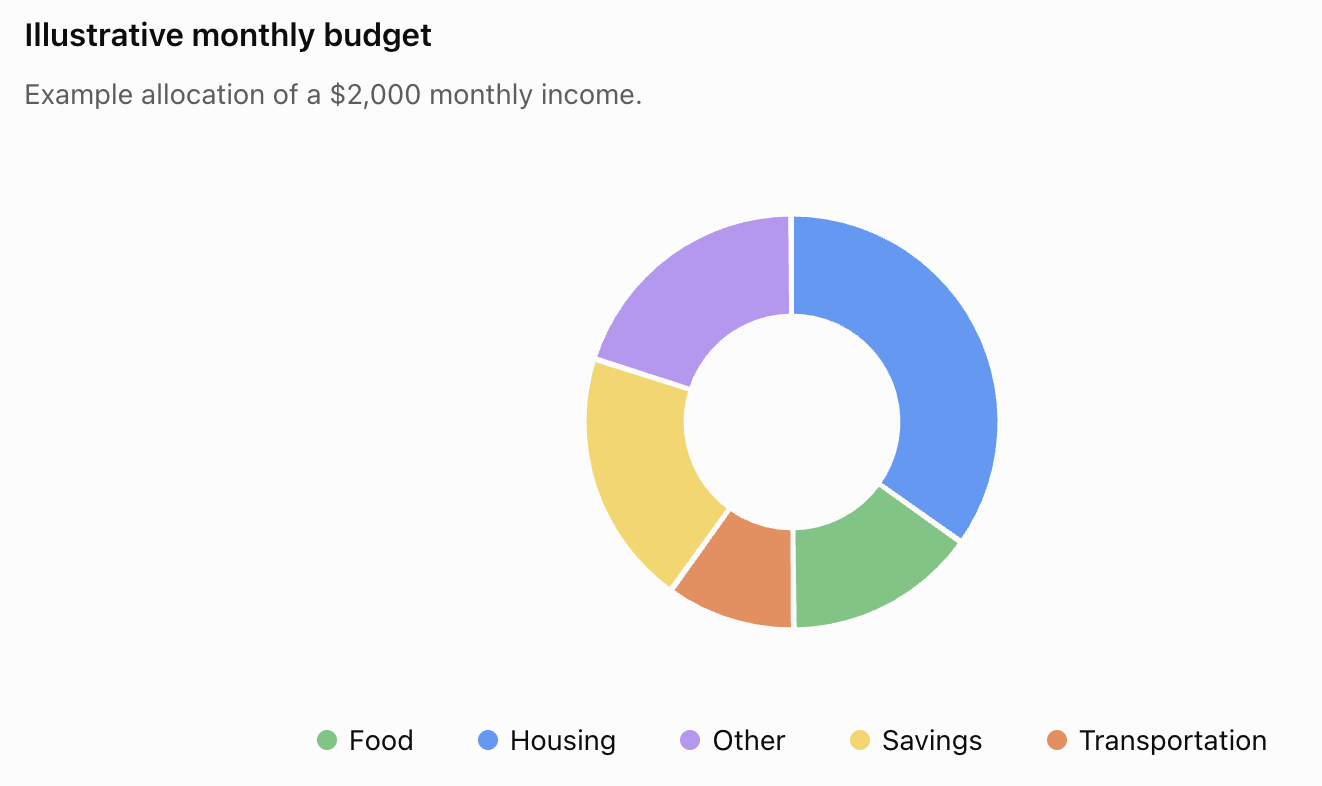
A chart makes it easier to see which categories account for the largest portions of the budget.
Reading Budget Tables
Consider this budget:
| Category | Planned | Actual |
|---|---|---|
| Food | $250 | $280 |
| Transportation | $120 | $105 |
| Entertainment | $100 | $135 |
| Clothing | $80 | $60 |
| Savings | $300 | $270 |
Tables allow us to compare what was planned with what actually happened.
Calculating Budget Differences
For food:
$280 − $250 = $30
Actual food spending was:
$30 above budget
Transportation:
$120 − $105 = $15
Actual transportation spending was:
$15 below budget
Entertainment:
$135 − $100 = $35
Actual entertainment spending was:
$35 above budget
These differences are called variances.
Interpreting Budget Data
A budget should not only be calculated. It should also be interpreted.
For example, the previous table suggests:
- food spending exceeded the planned amount by $30
- transportation spending was $15 below the planned amount
- entertainment exceeded the plan by $35
- clothing was $20 below the plan
- savings were $30 below the planned target
This information can help someone decide what adjustments to make in the next budget.
Planned vs Actual Spending
Charts can make differences easier to identify.
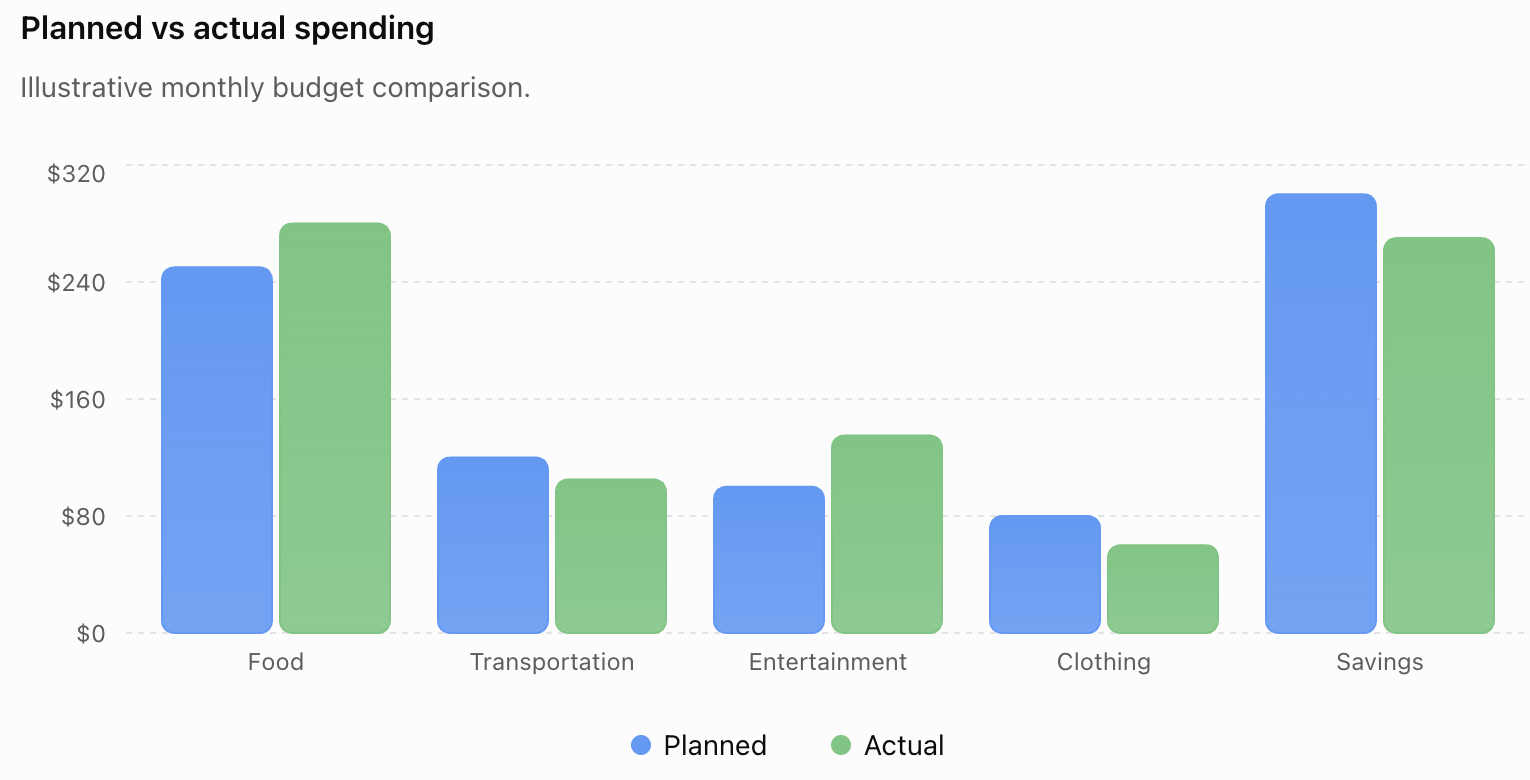
Graphs can reveal patterns that may be less obvious when looking only at individual numbers.
Comparing Financial Options
Mathematics can help compare different financial choices.
Suppose two phone plans are available.
Plan A:
$30 per month
Plan B:
$25 per month + $50 setup fee
For one month:
Plan A:
$30
Plan B:
$25 + $50 = $75
For 12 months:
Plan A:
12 × $30 = $360
Plan B:
12 × $25 + $50 = $350
The comparison changes depending on how long the service is used.


This shows why comparing only one advertised number can be misleading.
Comparing Unit Prices
Suppose:
Package A:
500 g for $4.50
Package B:
800 g for $6.40
Calculate cost per 100 g.
Package A:
500 g contains five groups of 100 g.
$4.50 ÷ 5 = $0.90 per 100 g
Package B:
800 g contains eight groups.
$6.40 ÷ 8 = $0.80 per 100 g
Unit rates make differently sized packages easier to compare.
Discounts and Budgets
Suppose an item normally costs:
$80
and is discounted by:
25%
Discount:
0.25 × $80 = $20
Sale price:
$80 − $20 = $60
If the shopping budget is $70:
$70 − $60 = $10
would remain.


Taxes and Final Prices
The displayed price is not always the final amount paid.
Suppose an illustrative purchase costs:
$120
and a tax of:
8%
is applied.
Tax:
0.08 × $120 = $9.60
Final cost:
$120 + $9.60 = $129.60
When budgeting for purchases, it is important to know whether additional charges are included in the listed price.
Tips and Service Charges
Suppose a restaurant bill is:
$60
and someone calculates a 15% tip.
Tip:
0.15 × $60 = $9
Total:
$60 + $9 = $69
In real situations, whether a tip or service charge applies depends on local practices and the bill itself.
Recurring Expenses
Small recurring expenses can become significant over time.
Suppose a subscription costs:
$12/month
Annual cost:
$12 × 12 = $144
Three similar subscriptions would cost:
3 × $144 = $432 per year


Converting recurring costs to annual amounts can make their financial impact easier to understand.
Daily Spending Over Time
Suppose someone spends:
$5 each school day
on an optional purchase.
Over 5 days:
$5 × 5 = $25
Over 20 school days:
$5 × 20 = $100
Over 180 school days:
$5 × 180 = $900
A relatively small repeated expense can become a much larger total over time.
Saving Toward a Goal
Suppose someone wants to save:
$1,200
and can save:
$150 per month
Calculate:
$1,200 ÷ $150 = 8
It would take:
8 months
assuming the same amount is saved each month.


Working Backwards from a Savings Goal
Suppose someone wants to save:
$2,400 in 12 months
Required monthly savings:
$2,400 ÷ 12 = $200
Therefore:
$200 per month
must be set aside on average.
If monthly income is $1,600:
$200 / $1,600 × 100% = 12.5%
The savings goal represents:
12.5% of monthly income
Emergency and Unexpected Expenses
Real budgets do not always follow the plan exactly.
Unexpected expenses can include:
- repairs
- replacement items
- medical or dental costs
- transportation problems
- urgent travel
- sudden changes in regular expenses
One way budgets can account for uncertainty is by including money for unexpected expenses or maintaining savings that are not already committed elsewhere.
The appropriate amount depends on the person's circumstances.
Comparing Short-Term and Long-Term Costs
Suppose:
Option A costs:
$20 per month
Option B costs:
$180 per year
Compare annual costs.
Option A:
$20 × 12 = $240/year
Option B:
$180/year
Comparing both options over the same time period provides a meaningful mathematical comparison.
The Cheapest Option Is Not Always the Best Decision
Cost is important, but financial decisions can involve more than price.
Other factors might include:
- quality
- reliability
- how long the product will last
- maintenance costs
- cancellation fees
- warranties
- convenience
- amount actually needed
For example, buying a larger package because it has a lower unit price may not save money if much of the product is wasted.
Mathematics provides evidence for a decision, but the context determines which factors matter.
Advertising and Financial Decisions
Advertisements often emphasize numbers such as:
50% OFF
Only $10/month
Buy 2, Get 1 Free
Save $100
These numbers can be useful, but they should be interpreted carefully.

Useful questions include:
- What was the original price?
- What is the final price?
- Are there additional fees?
- How long does the offer last?
- Is a subscription required?
- How much will it cost over a full year?
- How much of the product is actually needed?
Comparing Two Discounts
Store A offers:
20% off a $100 item
Discount:
$20
Final price:
$80
Store B sells the same item for:
$85 with a $10 coupon
Final price:
$75
The percentage advertised does not by itself determine the final cost.
Calculate the actual amount paid.
Using Percentages to Analyze Spending
Suppose monthly income is:
$2,400
and food spending is:
$480
Percentage of income spent on food:
480 / 2400 × 100%
= 20%
If transportation costs:
$240
then:
240 / 2400 × 100% = 10%
Percentages make categories easier to compare.
Comparing Spending Categories
Suppose someone spends:
Food = $500
Housing = $900
Transportation = $250
Entertainment = $150
Savings = $200
Total:
$2,000
Housing percentage:
900 / 2000 × 100% = 45%
Food percentage:
500 / 2000 × 100% = 25%
Transportation percentage:
12.5%
Entertainment percentage:
7.5%
Savings percentage:
10%
These percentages show how the total is distributed.


Financial Information in Tables
Suppose three savings plans are presented:
| Plan | Monthly Contribution | Annual Contribution |
|---|---|---|
| A | $50 | $600 |
| B | $75 | $900 |
| C | $100 | $1,200 |
A table helps us identify patterns and compare values quickly.
For example:
Plan C saves:
$1,200 − $600 = $600
more per year than Plan A.
But it also requires:
$50 more each month
The numbers describe the trade-off.
Financial Information in Graphs
Suppose a person's spending changes over several months.
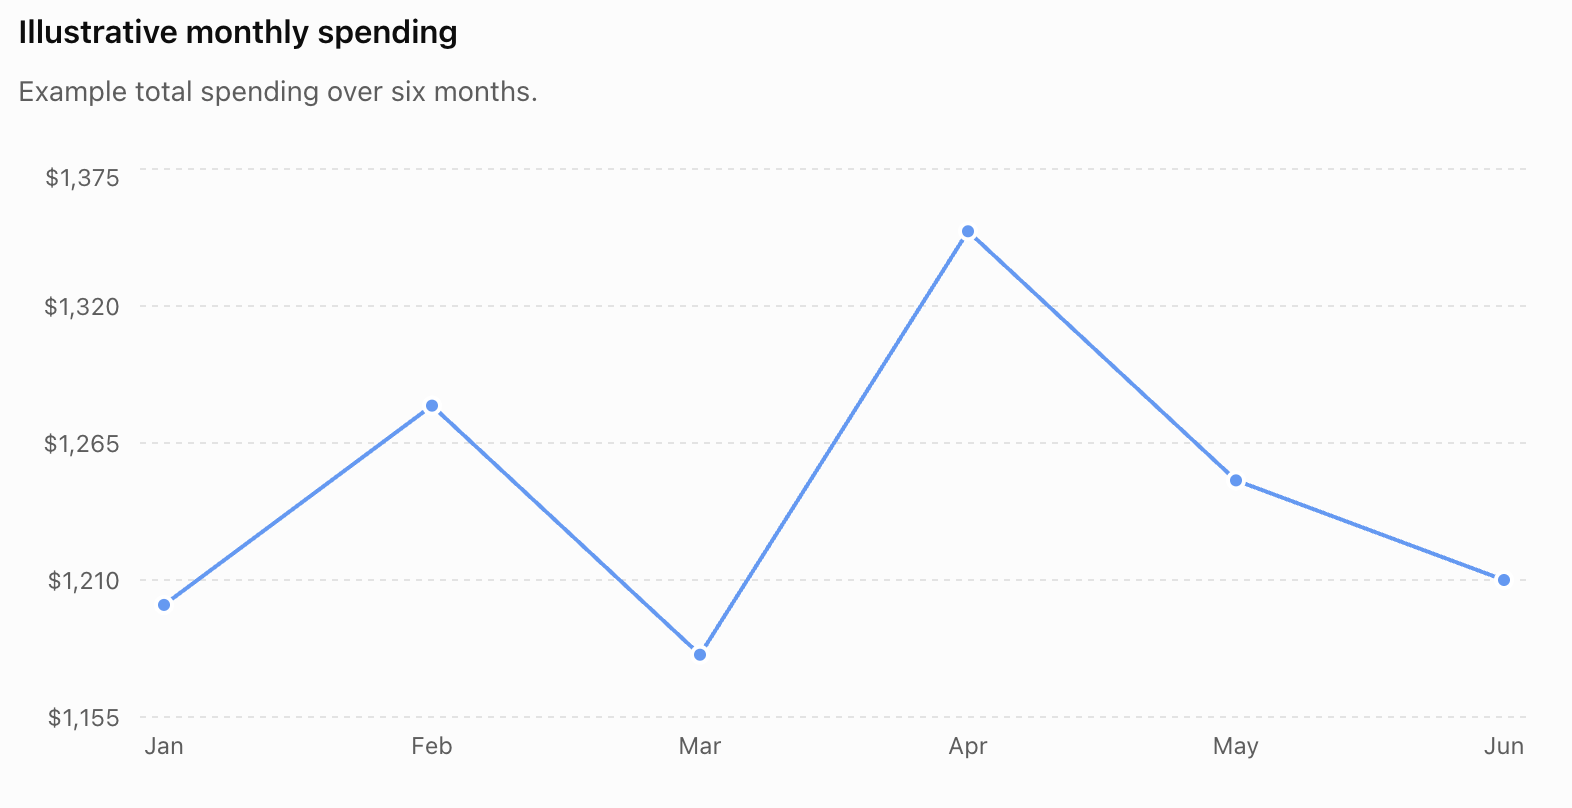
A graph can help identify:
- increases
- decreases
- unusually high months
- unusually low months
- overall patterns
However, the graph should be interpreted together with the actual values and context.
Checking Graph Scales
Graphs can sometimes make differences appear larger or smaller depending on the scale used.
Suppose two expenses are:
$100 and $105
The difference is only:
$5
If a graph's vertical axis begins at $99 instead of $0, the visual difference may appear very large.


When interpreting financial graphs, always check:
- axis labels
- units
- scale
- time period
- categories
- whether the graph begins at zero when relevant
- whether important information has been omitted
Percent Change in Expenses
Suppose an electricity bill increases from:
$80 to $100
Change:
$100 − $80 = $20
Percentage increase:
20 / 80 × 100% = 25%
Therefore:
the expense increased by 25%
Percentage changes can help compare increases involving different starting amounts.
Comparing Changes
Expense A increases:
$20 → $30
Increase:
$10
Percentage increase:
10 / 20 × 100% = 50%
Expense B increases:
$100 → $120
Increase:
$20
Percentage increase:
20 / 100 × 100% = 20%
Expense B increased by more dollars, but Expense A had the larger percentage increase.
This demonstrates why both absolute and percentage changes can be useful.
Making Decisions with Numerical Data
Suppose you have:
$500
available for a purchase.
Option A:
Purchase price = $420
Expected additional cost = $30
Total:
$450
Money remaining:
$50
Option B:
Purchase price = $390
Expected additional cost = $90
Total:
$480
Money remaining:
$20
Looking only at the purchase price would make Option B appear less expensive.
Calculating the total cost changes the comparison.
Opportunity Cost
Financial choices often involve opportunity cost.
Opportunity cost is the value of what is given up when one option is chosen instead of another.
Suppose someone has:
$100
They could spend $100 on entertainment or save the $100 toward a future goal.
If they spend it, the opportunity cost includes the savings they could have kept.
Opportunity cost is not always a simple dollar calculation, but numerical information can help make the trade-off clearer.
Budget Constraints
A constraint is a limit or condition.
Suppose you have:
$300
to organize an event.
Possible costs:
Food = $140
Decorations = $60
Equipment = $75
Total:
$140 + $60 + $75 = $275
Money remaining:
$300 − $275 = $25
The $300 budget acts as a constraint.
Any plan costing more than $300 would exceed the available budget.
Worked Example 1: Monthly Budget
Income:
$1,800
Expenses:
Housing = $650
Food = $300
Transportation = $180
Phone = $50
Entertainment = $120
Other = $100
Total expenses:
650 + 300 + 180 + 50 + 120 + 100
= $1,400
Remaining:
$1,800 − $1,400 = $400
Answer:
$400 remains
Worked Example 2: Savings
Income:
$2,500
Savings goal:
18% of income
Calculate:
0.18 × $2,500 = $450
Answer:
$450
If other expenses total $1,850:
$2,500 − $450 − $1,850 = $200
remains after savings and expenses.
Worked Example 3: Comparing Offers
Option A:
$15/month for 12 months
Total:
15 × 12 = $180
Option B:
$120 for the first 6 months + $12/month for the next 6 months
Total:
$120 + (6 × $12)
= $192
Comparing total costs over the same 12-month period provides a consistent basis for comparison.
Worked Example 4: Discount
A backpack costs:
$75
Discount:
20%
Discount amount:
0.20 × $75 = $15
Sale price:
$75 − $15 = $60
If the budget is $70:
$70 − $60 = $10
remains.
Worked Example 5: Spending Percentage
Monthly income:
$3,000
Housing:
$1,050
Percentage:
1050 / 3000 × 100%
= 35%
Therefore:
35% of income is allocated to housing
in this example.
Worked Example 6: Savings Goal
Goal:
$900
Current savings:
$300
Still needed:
$900 − $300 = $600
If $75 is saved each month:
600 ÷ 75 = 8 months
Answer:
8 additional months
assuming the saving rate remains constant.
Worked Example 7: Budget Adjustment
Income:
$1,500
Expenses:
$1,620
Deficit:
$1,620 − $1,500 = $120
To balance the budget, the person would need some combination of:
- reducing planned expenses by $120
- increasing income by $120
- or making changes totaling $120
The mathematics identifies the size of the gap.
Worked Example 8: Unit Price
Package A:
12 items for $18
Unit price:
18 ÷ 12 = $1.50/item
Package B:
20 items for $28
Unit price:
28 ÷ 20 = $1.40/item
The unit prices are:
$1.50/item versus $1.40/item
Other factors such as how many items are actually needed may also matter.
Worked Example 9: Annual Cost
A service costs:
$8.99/month
Approximate annual cost:
$8.99 × 12 = $107.88
A monthly price that appears small can therefore represent a much larger annual expense.
Worked Example 10: Multi-Step Purchase
A device costs:
$500
Discount:
15%
Discount amount:
0.15 × $500 = $75
Discounted price:
$500 − $75 = $425
Suppose an illustrative 8% tax is then applied:
0.08 × $425 = $34
Final price:
$425 + $34 = $459
Notice that the tax was calculated on the discounted price in this example.
Estimation and Financial Decisions
Estimation is useful when checking financial calculations.
Suppose:
18% of $498
is needed.
Estimate:
20% of $500 ≈ $100
Exact calculation:
0.18 × 498 = $89.64
The exact value is reasonably close to the estimate.
If a calculator produced:
$896.40
we would know something was probably wrong.


A Budget Is a Model
A budget is not a prediction that every expense will occur exactly as planned.
It is a mathematical model of expected income and spending.
Actual values can change.
For this reason, useful budgeting involves comparing:
planned values
with:
actual values
and then updating future plans.
A Reliable Financial Problem-Solving Strategy
When solving a budgeting or money problem:
Step 1: Identify the financial goal or question.
Step 2: Identify the relevant income, costs, percentages, and time periods.
Step 3: Make sure values are being compared over the same period.
Step 4: Calculate total income.
Step 5: Calculate relevant expenses.
Step 6: Find unit rates, percentages, or total costs when needed.
Step 7: Compare the numerical results.
Step 8: Check whether the answer fits the budget constraint.
Step 9: Estimate to check reasonableness.
Step 10: Explain what the numbers show before making a decision.
Common Mistakes
Mistake 1: Comparing monthly and annual costs directly
Convert them to the same time period first.
Mistake 2: Looking only at the advertised price
Additional fees, taxes, recurring charges, or required purchases may affect total cost.
Mistake 3: Confusing a discount with the final price
A $20 discount does not mean the item costs $20.
Mistake 4: Ignoring recurring costs
A small monthly expense can become significant over a year.
Mistake 5: Assuming the lowest unit price always means the lowest total spending
A larger package may have a lower unit price but require spending more money overall.
Mistake 6: Forgetting the original value when calculating percentage change
Use:
percentage change = change / original value × 100%
Mistake 7: Treating planned spending as actual spending
Budgets are plans. Actual spending should be recorded and compared with the plan.
Mistake 8: Ignoring graph scales
Always examine labels, units, intervals, and the range shown.
Did You Know?
Budgeting combines many mathematical skills rather than being a completely separate type of mathematics.


Budgeting can involve:
- addition and subtraction
- multiplication and division
- decimals
- fractions
- percentages
- ratios
- unit rates
- proportions
- tables
- graphs
- estimation
- data analysis
This makes budgeting an important real-world application of many mathematical ideas.
Key Terms
- Budget: Plan for income, spending, and saving.
- Income: Money received.
- Expense: Money spent.
- Fixed expense: Expense that generally remains constant over a particular period.
- Variable expense: Expense that can change.
- Savings: Money kept for future use rather than currently spent.
- Savings rate: Savings expressed as a percentage of income.
- Surplus: Amount by which income exceeds expenses.
- Deficit: Amount by which expenses exceed income.
- Balance: Amount remaining after expenses are subtracted from income.
- Budget constraint: Limit on how much money is available.
- Unit price: Cost for one item or one standard unit.
- Discount: Reduction from an original price.
- Tax: Amount added or collected according to an applicable tax system.
- Recurring expense: Expense that occurs repeatedly.
- Variance: Difference between a planned amount and an actual amount.
- Opportunity cost: Value of an alternative given up when a choice is made.
- Percentage change: Change expressed relative to the original amount.
Key Equations
Budget balance:
Balance = Income − Expenses
Savings rate:
Savings rate = Savings / Income × 100%
Percentage of income spent:
Spending percentage = Expense / Income × 100%
Unit price:
Unit price = Total cost / Quantity
Discount amount:
Discount = Original price × Discount rate
Sale price:
Sale price = Original price − Discount
Percentage change:
Percentage change = Change / Original value × 100%
Key Takeaways
- A budget is a mathematical plan for managing income, expenses, and savings.
- Income is money received, while expenses are money spent.
- When income exceeds expenses, there is a surplus.
- When expenses exceed income, there is a deficit.
- Savings can be expressed as an amount or as a percentage of income.
- Fixed and variable expenses behave differently and can affect how easily a budget can be adjusted.
- Tables help organize financial information.
- Charts help reveal patterns and differences in spending.
- Planned and actual spending should be compared.
- Unit prices allow products of different sizes to be compared.
- Monthly and annual costs should be converted to the same time period before comparison.
- Discounts, taxes, fees, and recurring costs can affect the final amount paid.
- Percentage calculations can show how much of income is spent or saved.
- Percentage change helps compare increases and decreases.
- Advertised prices should be interpreted in the context of total cost.
- The least expensive option is not automatically the most appropriate option because quality, quantity, reliability, and other constraints may matter.
- Estimation helps identify unreasonable calculations.
- A budget is a model and may need to change when actual income or expenses change.
- Numerical data can clarify trade-offs and consequences.
- Financial mathematics does not make a decision for us; it provides evidence that helps us understand the available options.